The temporary measure that never ended: the Nixon shock at 55
On 15 August 1971, Richard Nixon suspended the dollar's convertibility to gold. He called it temporary. Fifty-five years on, the word still applies — because what replaced Bretton Woods was never formally designed at all.
On a Sunday evening in August 1971, Richard Nixon interrupted the most-watched television programme in America to make an announcement. He spoke of international speculators, of defending the American worker, and of a set of measures — some domestic, some targeted at trade — that he packaged as the New Economic Policy. Near the middle of the speech, almost as an aside, he mentioned that the United States would temporarily suspend the convertibility of the dollar into gold.
Temporary.
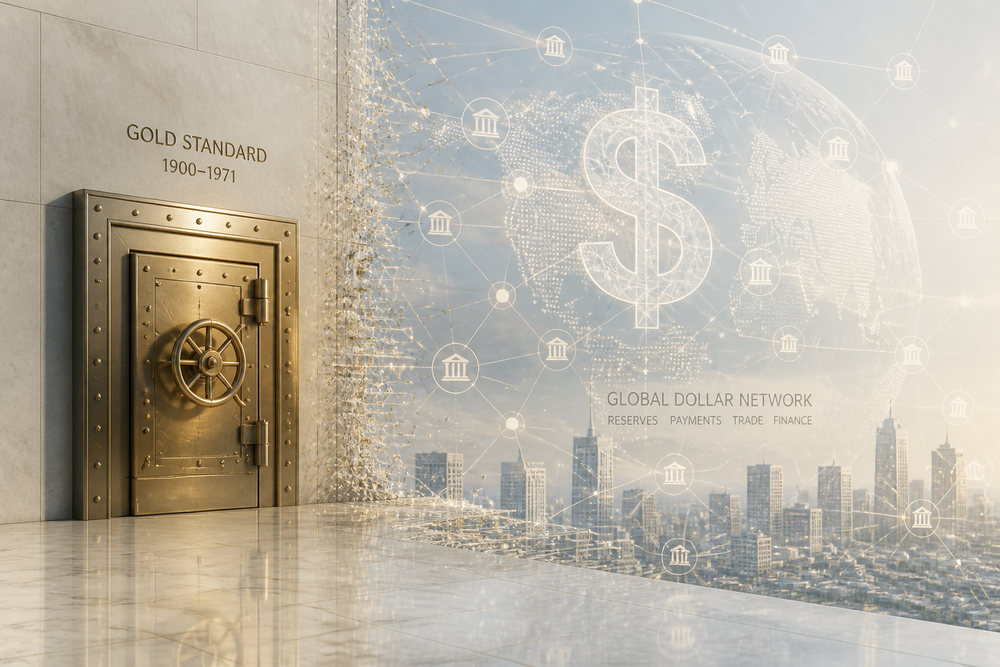
Fifty-five years later, that suspension is still in place. The global monetary system that emerged from its aftermath — floating exchange rates, dollar dominance without a gold anchor, a financial architecture built on liquidity and network effects rather than metal — was not designed on that Sunday night. It was improvised over the two years that followed, and has been improvised, amended and defended ever since. Nixon's "temporary" measure did not end an era; it revealed what was already holding money together, once the gold promise was gone.
A system that contained its own contradiction
To understand the shock, it helps to understand what Bretton Woods actually was — and why it was already failing before Nixon appeared on television.
In 1944, the allied nations assembled at Bretton Woods, New Hampshire, to design the post-war financial order. The result was a system of fixed but adjustable exchange rates: each currency pegged to the dollar, the dollar convertible into gold at $35 per ounce for foreign monetary authorities. Capital controls and IMF supervision were built in. It was a managed system, not a free-market one, and for the first two post-war decades it worked. Trade expanded. Exchange rates held. Europe and Japan rebuilt.
The problem was structural. The world needed dollars — for reserves, for trade, for liquidity. For the world to get dollars, the United States had to run external deficits: spending abroad, investing abroad, stationing troops abroad. But those dollars were potential claims on US gold reserves at the fixed price. As Europe and Japan recovered, their dollar holdings grew. US gold did not.
This is the Triffin dilemma, named after the Belgian-American economist Robert Triffin, who identified it in the early 1960s. The dollar's dual role — national currency and global reserve — required America to supply the world with the thing that was notionally redeemable for something scarce. Eventually, the mathematics became inescapable. By mid-August 1971, US official reserve liabilities exceeded US gold and reserve assets by nearly $30 billion. The IMF's own institutional history is blunt about it: the gold convertibility promise could no longer be honoured at scale.
Bretton Woods had not been in good health for years. A two-tier gold market was introduced in 1968, separating central bank transactions from private trading. Canada and West Germany had already let their currencies move away from fixed parities. Private capital flows had grown large enough to overwhelm official interventions. The question facing the world in August 1971 was not whether adjustment would happen. It was who would bear it — and who would decide.
Camp David: crisis management as leverage
What made the Nixon Shock distinctive was not the economic necessity; it was the politics.
On 12 August 1971, Nixon, Treasury Secretary John Connally and OMB director George Shultz settled on a package combining domestic and international measures. Over the following weekend at Camp David, a tightly held group — notable for the absence of the State Department and the National Security Council — worked through the details. Henry Kissinger, who would later describe himself as not fully aware of the meeting's implications, was not consulted about a decision of major foreign-policy significance. The foreign economic record from that period, published by the State Department, makes clear that this was deliberate. Connally in particular wanted the announcement to land as a fait accompli.
The three components mattered in combination. Suspending gold convertibility stopped the immediate reserve drain. Wage and price controls addressed the domestic inflation that had been eroding US competitiveness. The 10% import surcharge was the instrument of leverage: it gave Washington a pressure point to use against trading partners who were reluctant to let their currencies rise against the dollar. The surcharge meant that America was not simply accepting a weaker dollar and hoping for the best. It was demanding that others help correct the imbalance, on American terms, under American pressure.
When Paul Volcker — then the Treasury's senior international monetary official, and a decade later the Federal Reserve chairman whose interest-rate campaign would break the inflation of the 1970s — met France's Finance Minister Valéry Giscard d'Estaing a few days later to explain the US position, he told him that the duration of the gold suspension depended on restoring a strong US external position. France had been the most vocal European challenger of US monetary policy — under President de Gaulle, Paris had systematically converted dollar reserves into gold — making Giscard the key interlocutor. That framing — provisional, conditional, awaiting a new bargain — is accurate as far as it goes. It is not an accurate description of a plan to keep the dollar untethered from gold permanently. The administration did not secretly decide on a permanent fiat world that Sunday. What it decided was to use the leverage of the moment to reshape the international distribution of adjustment costs. The permanence came later, by default.
The repair that didn't hold
Foreign governments were shocked. The European Community issued protests. Japan's Ministry of Finance scrambled. After months of negotiation, the G-10 reached the Smithsonian Agreement in December 1971: a general realignment of currencies against the dollar, an average depreciation of roughly 12% for the dollar against major trading partners, and wider bands for allowable exchange-rate fluctuations.
The Smithsonian Agreement is the part of this story that anniversary coverage tends to skip. Nixon called it the greatest monetary agreement in the history of the world, which tells you something about his rhetorical habits and almost nothing about the agreement's durability. It lasted fourteen months.
A further dollar devaluation followed in February 1973. In March 1973, leading countries abandoned fixed parities entirely and generalised floating began. This is the more accurate date for the full transition to the floating-rate system that exists today — not 15 August 1971. The Nixon Shock ended the gold conversion obligation and made the old system dysfunctional; it was the Smithsonian's failure and the broader float of 1973 that settled what would replace it.
What replaced it was not designed by anyone. It was the dollar — freed from the gold promise but retained by markets, by network effects, by the sheer depth of US financial markets and the absence of a comparable alternative. The dollar remained the world's primary reserve currency not because America promised anything new, but because no one else could offer what it already had.
Did cutting gold loose detach money from reality?
This is the version of the story that circulates most widely in heterodox economic commentary, in gold-bug forums and in certain corners of financial history. The claim is that 15 August 1971 was the moment money became untethered from anything real — that fiat money allowed finance to grow parasitically on top of a productive economy, that the Volcker disinflation of the early 1980s (the Federal Reserve's deliberate campaign of sharply raised interest rates to crush double-digit inflation), the financial crises of 1997–98 and 2008, and the growth of financial services as a share of GDP (gross domestic product, a measure of total economic output) can all be traced back to that Sunday television address.
There is something to the observation, but the monocausal version does not hold up.
The end of gold convertibility removed one specific external constraint on the dollar: the obligation to convert it into metal at a fixed price. It did not remove the constraints that actually determine whether an economy functions — inflation, fiscal capacity, productive competitiveness, external balance, political consent. The 1970s made this clear. The United States ran inflation that reached double digits precisely because the removal of the gold constraint, combined with oil shocks, loose monetary policy and fiscal expansion, had real consequences. The Volcker disinflation of 1979–82 — in which Federal Reserve chairman Paul Volcker raised interest rates above 20 per cent, deliberately inducing a recession, to bring inflation down from a peak of around 13 per cent — was brutal, deliberate and politically costly, but it demonstrated that fiat money cannot simply run ahead of reality without eventually being forced to stop.
The growth of financial markets after 1971 has multiple causes: deregulation beginning in the 1970s and accelerating through the 1980s, information technology that reduced transaction costs, the expansion of pension funds and institutional investors, tax and corporate-governance changes that incentivised financial returns over capital investment, and monetary policy choices across several decades. Attributing this to a single speech underestimates the role of politics, technology and policy in shaping financial structures.
The petrodollar account — in which the oil-for-dollar arrangement engineered after 1973 rescued the dollar from the collapse of Bretton Woods — has similar problems. Dollar oil invoicing did reinforce dollar demand. The recycling of oil-exporter surpluses through US financial markets did matter. But the dollar had already held its position as the dominant reserve and settlement currency because there was no alternative at scale: no other market large enough, liquid enough, and open enough to park reserves at global volume. The petrodollar story treats chronological proximity as causality.
Why the dollar remained central
The paradox at the heart of this anniversary is genuine. Nixon removed the gold promise. The dollar became more central.
In the fourth quarter of 2025, the IMF's currency composition of official foreign-exchange reserves data put the dollar at 56.77% of allocated global reserves. The euro stood at 20.25%; the renminbi at 1.95%. The dollar's share has declined from the post-Bretton Woods highs, but the decline has been gradual, and the gap between the dollar and every alternative remains very large.
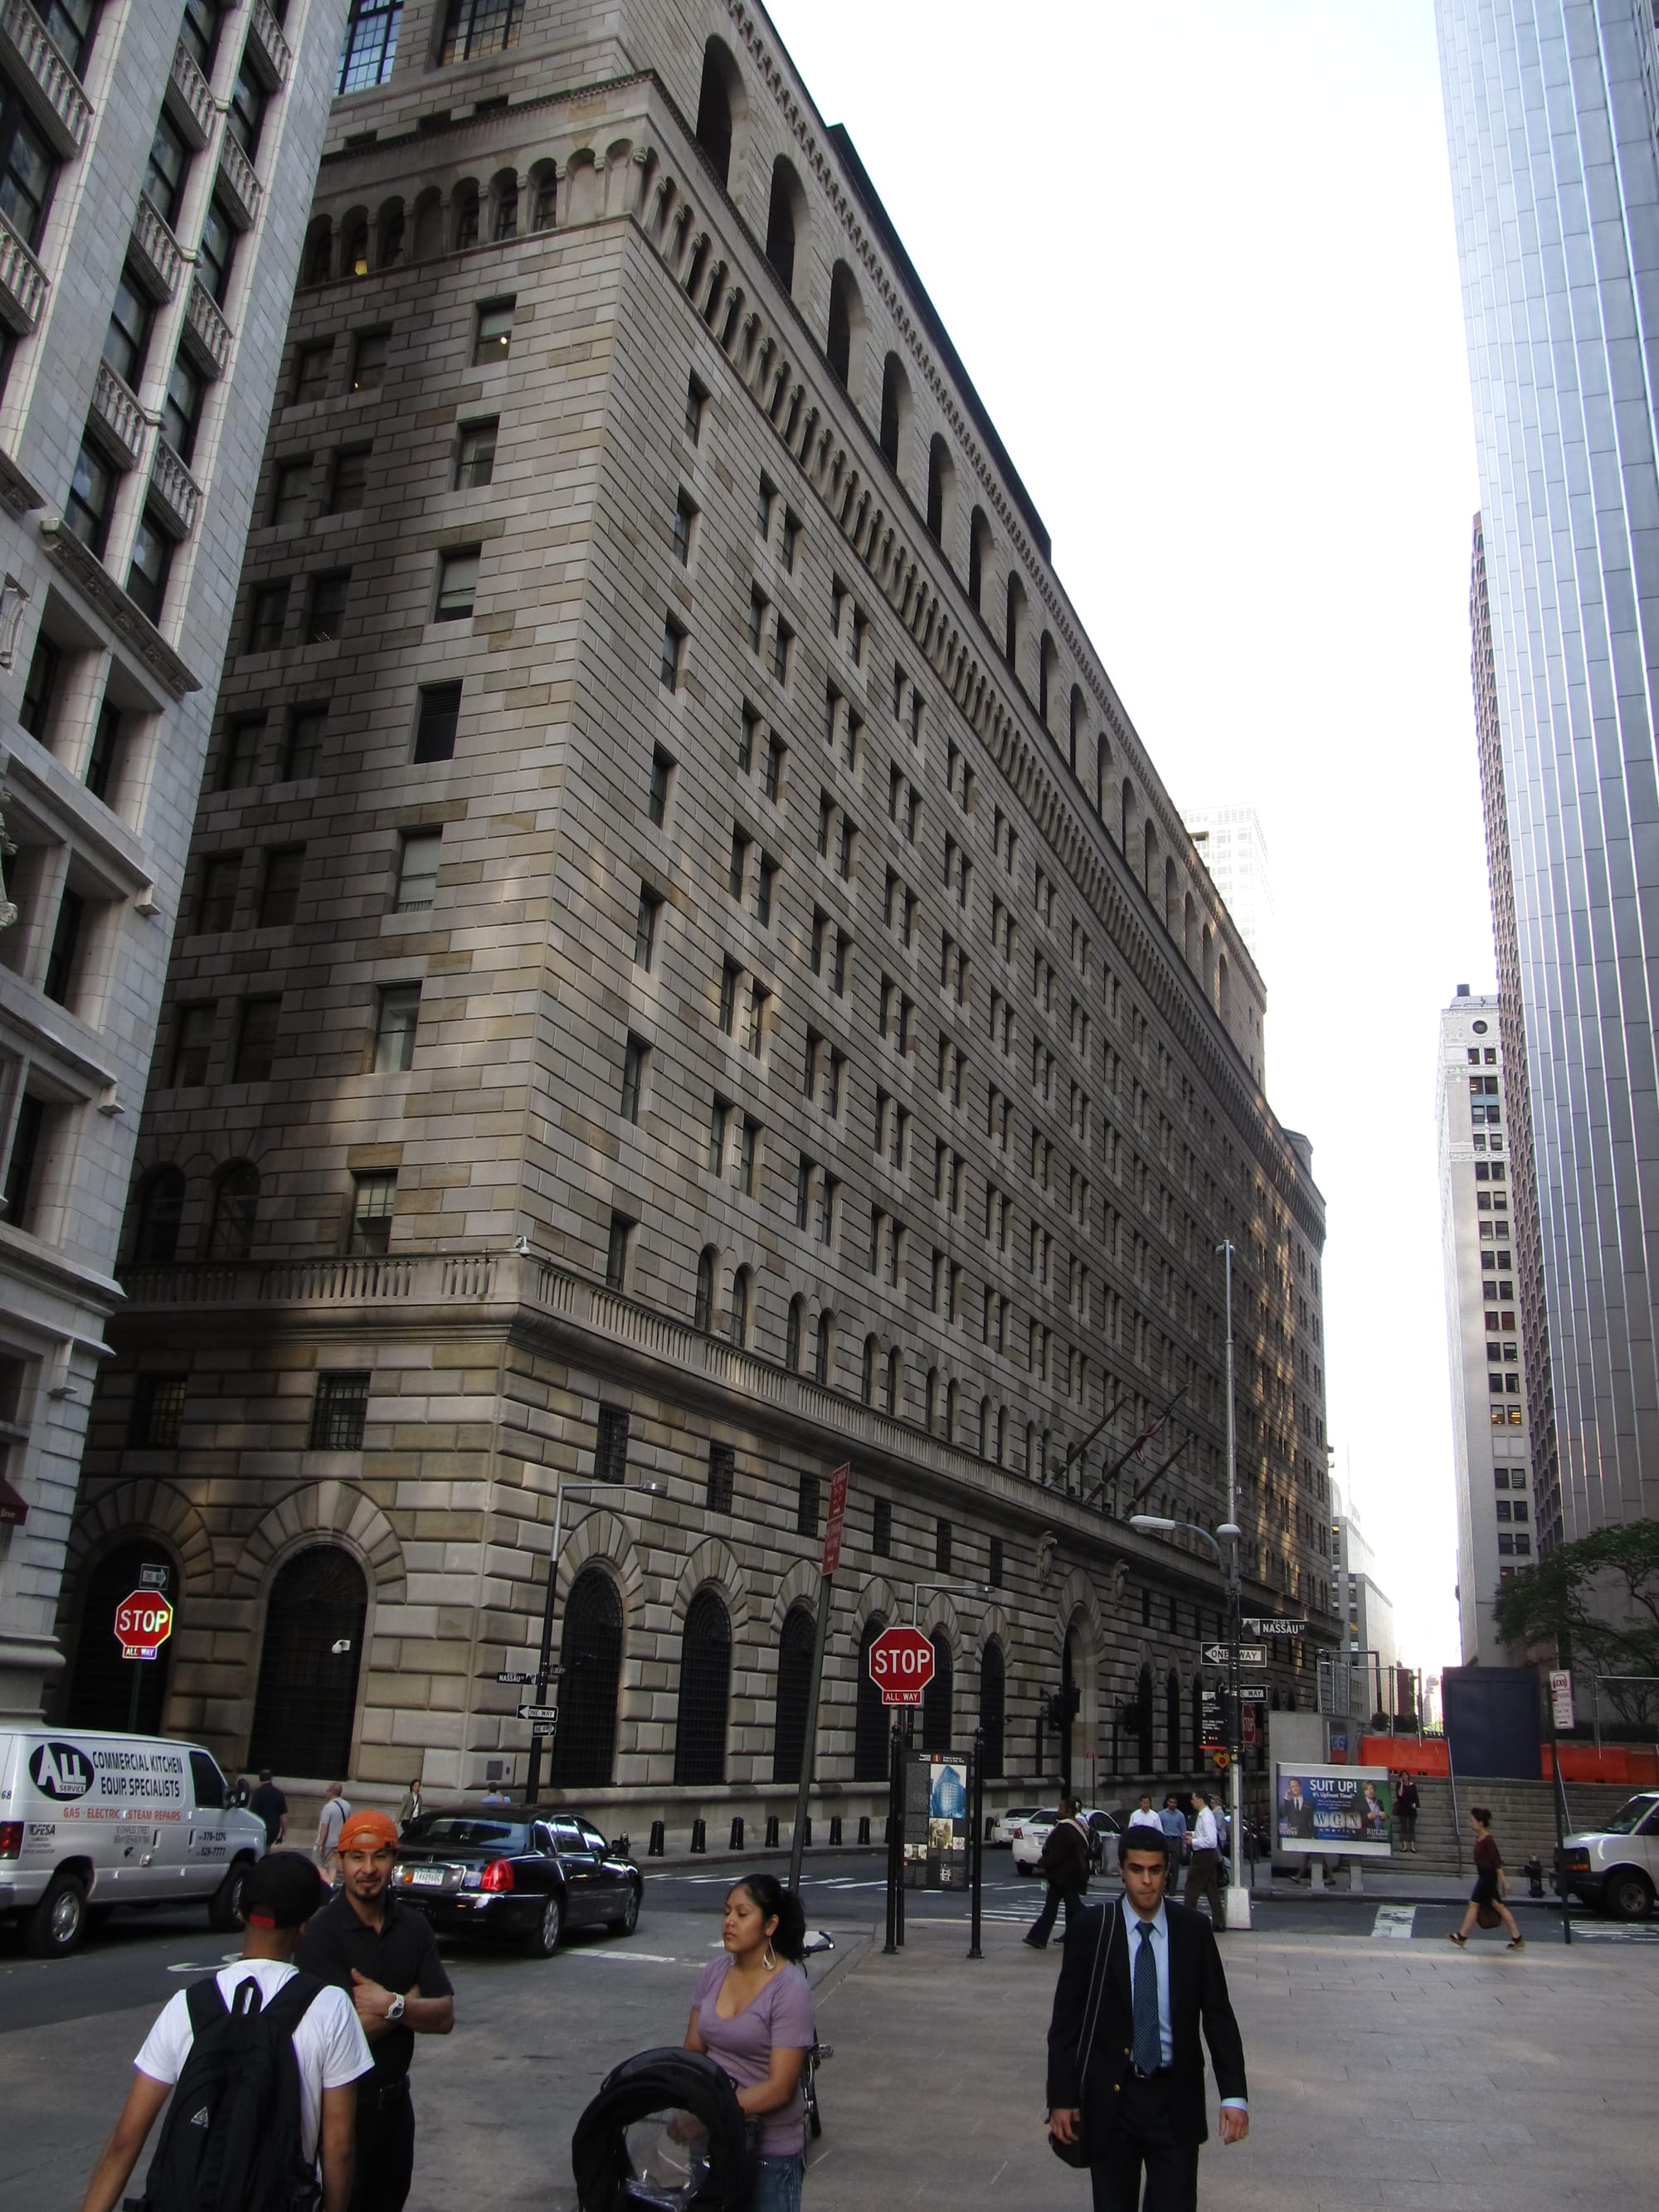
Reserve-currency power rests on a package of things, not a single promise. It requires a vast stock of liquid government securities. It requires private markets that investors can enter and exit at scale without moving the price. It requires a legal and institutional framework that works — not perfectly, but predictably enough that foreigners trust it as a place to park savings under stress. It requires the network effects that come from dollar invoicing, dollar debt markets, and dollar-denominated contracts across commodities, shipping, and finance. And it requires central-bank swap lines and liquidity arrangements that the Federal Reserve has extended to allied central banks as lender of last resort.
This package cannot be replicated by political announcement. "BRICS currency" rhetoric — proposals, among the BRICS grouping (Brazil, Russia, India, China and South Africa, since expanded to include several more countries), for a shared reserve asset or payment system outside the dollar — has circulated for years. It reflects genuine political dissatisfaction with US dollar dominance, particularly after American use of financial sanctions following Russia's invasion of Ukraine in 2022 demonstrated that dollar-denominated reserves can be frozen. BRICS members can increase local-currency trade settlements and develop parallel payment systems that reduce their exposure to US clearing infrastructure. These are meaningful steps. But a common reserve asset requires something harder: a single place to park savings at scale, with predictable rules, deep liquid markets, and credible enforcement. The BRICS group includes countries with incompatible capital account policies, different inflation histories, different legal traditions and active geopolitical rivalries with each other. A multipolar payments world — diversified, parallel, useful for reducing sanctions exposure — is achievable. A multipolar reserve world requires a monetary infrastructure that does not yet exist.
The dollar's most agile new emissaries
The contemporary monetary technology that carries the Nixon Shock's echo most clearly is not gold. It is stablecoins.
The appeal of privately issued digital money as an alternative to state-backed currency has a surface-level resonance with the 1971 narrative: if governments cannot be trusted with the money supply, perhaps digital assets offer an escape. But data from the BIS — the Bank for International Settlements, a Basel-based institution that acts as a bank for the world's central banks and publishes authoritative research on global monetary flows — puncture that story efficiently. As of 2026, 99.4% of fiat-backed stablecoins by market value are pegged to the US dollar. What reads as a flight from sovereign money is, in most cases, a more agile distribution system for the most sovereign money of all.
Stablecoins do some things that are genuinely new: they lower access barriers for dollar use in economies with limited banking infrastructure, they reduce friction in cross-border transfers, and they operate at hours and speeds that correspondent banking does not. These are real capabilities. But the BIS's assessment — that stablecoins in their current form fail the monetary tests of singleness, elasticity and integrity that make them unsuitable as the mainstay of any monetary system — is a reasonable verdict on the gap between the rhetoric and the architecture.
The most likely future is not stablecoins replacing the dollar, nor gold reasserting itself, nor a BRICS currency emerging in reserve-worthy form within the next decade. It is something more incremental: a dollar-centric system in which the distribution channels for dollar claims have multiplied and diversified, in which other currencies have carved out larger niches in regional trade, and in which the political contestation of dollar dominance continues without yet producing a credible structural alternative.
What the shock revealed
On 15 August 1971, Richard Nixon told Americans and the world that the gold window was closed — temporarily. The word was not dishonest, exactly. The administration genuinely expected a new monetary agreement to follow, one that would restore some version of exchange-rate order. The Smithsonian Agreement was that attempt. It failed. By 1973 the major currencies were floating, the gold obligation was gone for good, and no one had formally decided to build a fiat-dollar world. It had simply become the world that existed.
What the shock revealed was that the dollar's power was never really about the gold. It was about institutions: the depth and liquidity of US financial markets, the network of dollar-denominated trade and debt, the political and legal infrastructure that made dollar claims worth holding even under stress. Gold was the external constraint that made the post-war bargain legible — a visible promise that anchored confidence. When Nixon removed it, he did not dissolve the dollar's power. He revealed that the power had already migrated somewhere else.
The irony is that the act often blamed for loosening money from reality — a president cutting the link between the dollar and the oldest monetary metal — actually demonstrated the opposite. Fifty-five years on, the dollar is not dominant because America promises anything. It is dominant because no alternative offers the combination of depth, openness and institutional trust that dollar markets provide. That is not a gold promise. It is something more durable: a network that would take decades to replicate, and that no political announcement has yet managed to replace.
Nixon did not make the dollar less central by cutting it loose from gold. He revealed that monetary power had already moved — from metal to markets, from promise to infrastructure, from a fixed price to a global system that runs, provisionally, on trust.
Sources
Primary documents and archives
- Nixon and the End of the Bretton Woods System, 1971–1973 — U.S. Office of the Historian — State Department milestone overview of the Nixon Shock and its diplomatic aftermath
- Camp David, 13 August 1971 — FRUS 1969–76, Vol. III — Primary diplomatic record of the Camp David weekend meeting
- Preparation for the New Economic Policy, 11–12 August 1971 — FRUS 1969–76, Vol. III — Internal deliberations in the days before the announcement
- Volcker–Giscard conversation, 17 August 1971 — FRUS 1969–76, Vol. III — Volcker's explanation to France of the US position and conditions for restoring gold convertibility
- 15 August 1971 archive — Nixon Presidential Library — Presidential archive materials for the day of the announcement
- Annual Report FY1972 — U.S. Treasury / FRASER — Treasury's own account of the international monetary developments of 1971–72
IMF
- The Rethinking of the International Monetary System — IMF Blog, Atish Ghosh (2021) — IMF retrospective on the Bretton Woods era and the transition to floating rates
- The Par Value System in Retrospect: Achievements — IMF eLibrary — Institutional history of the fixed exchange-rate system's functioning and limits
- Collapse of the Par Value System (January–August 1971) — IMF eLibrary — Detailed account of the reserve-liability imbalance and the breakdown of gold convertibility
- Gold in the IMF — IMF Factsheet — IMF's current position on gold and how the 1971 changes affected its role
- IMF COFER Data Brief, Q4 2025 — Currency composition of official foreign-exchange reserves; source for the 56.77% dollar share figure
- Dollar's Share of Reserves Held Steady… — IMF Blog (2025) — IMF analysis of reserve-currency trends, adjusted for exchange-rate movements
BIS
- Annual Economic Report 2026 — BIS — BIS assessment of stablecoins and their fit against monetary singleness, elasticity and integrity criteria
- Annual Economic Report 2025, Chapter III — BIS — Detailed BIS analysis of stablecoin market composition and dollar dominance in digital assets
World Bank
- Global Financial Development Database — World Bank — Data on financial sector development used to contextualise post-1971 financialisation trends